

Stablecoin is evolving beyond a faster method for cross-border transfers into modern financial infrastructure, and becoming a layer for holding value, managing treasury, and developing products across embedded balances, wallets, cards, and programmable services.
According to a new Payoneer study, early adopters of the technology are already observing improvements across money movement speed, market access, and user experience, and recognizing the potential of stablecoins to develop innovative embedded financial solutions.
The study surveyed 265 senior payments, treasury and finance leaders in September 2026 at US-based marketplaces, platforms and enterprises with US$100 million or more in annual revenue already using, piloting, or evaluating stablecoin. It found that almost no one has walked away from the technology. In fact, 69% of respondents are live with stablecoins, bringing the total to 97% either using, testing, or still evaluating it today.
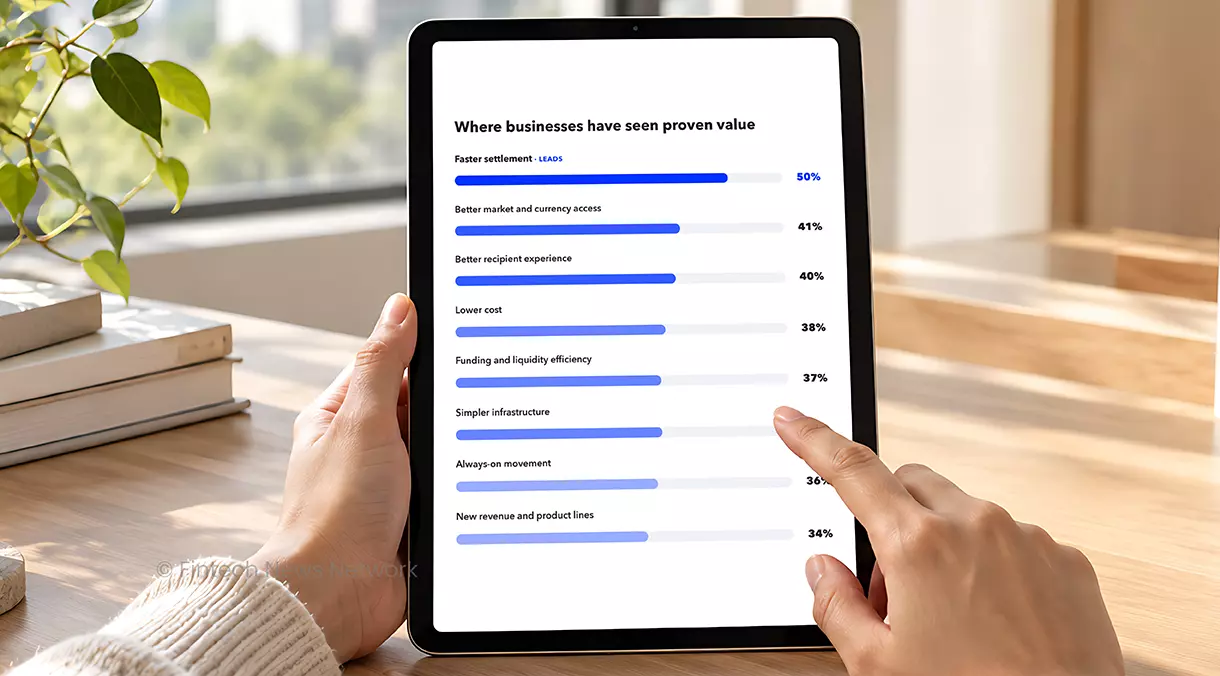
The study also found that organizations adopting stablecoins are already realizing benefits. Among those using or piloting stablecoin, 50% reported faster settlement, 41% cited better access to markets and currencies, and 40% cited a better experience for payment recipients.


It identified two main groups of adopters, with the largest users seeing the strongest gains. These “meaningful-scale users”, which are the businesses running stablecoin in operational use at significant volume across their organization, are more than three times as likely to call stablecoin very valuable compared with businesses still in pilot.
These organizations are also more than twice as likely to put the technology in front of their own customers, and run more than twice as many use cases, about four each versus fewer than two for everyone else.

The study also found that firms moving more money across borders tend to view stablecoins as very valuable. Among the largest movers with over US$1 billion in annual cross-border volume, 65% described stablecoins as very valuable, whereas only 43% of the smallest movers with under US$50 million in annual cross-border volume did so.
Organization size also influences outcomes, with multinationals reporting greater benefits. Of the businesses operating in 11 or more countries, 82% reported proven, measurable value in at least three areas, against 60% of those in ten countries or fewer.

The research also found that payments and finance teams are leading stablecoin adoption at US firms. Payments teams were cited by 48% of organizations, and finance and treasury teams by 41%, as the strongest drivers for adopting or expanding stablecoin efforts.
Leading these changes and stablecoin adoption at these US firms are payments and finance teams. 48% of organizations cited payments teams, and 41% cited finance and treasury teams, as their strongest sources of motivation to adopt or expand stablecoin initiatives.
Customer demand is the strongest pull from outside, cited by 35% of respondents, with seller and supplier demand close behind, named by 25% and 24% of respondents, respectively.

Top stablecoin applications
The study also found that at US firms, stablecoins are adopted by three main uses, namely satisfying recipient demand, moving money more efficiently, and building embedded financial experiences.
In markets experiencing significant economic instability like Argentina, a freelancer may prefer payments in USD to guard earnings from peso devaluation and inflation, preserve purchasing power, and secure stability. This creates genuine demand for USD-denominated stablecoins.
In treasury operations, stablecoins allow money to be transferred and settled 24/7, reducing delays, the need for advance funding, and the amount of working capital companies must keep available. This offers businesses a faster, cheaper, and more reliable way to move money globally without being restricted by banking hours, holidays or cross-border payment delays, improving liquidity and supporting more efficient payment management.
Finally, stablecoins allow marketplaces to offer financial products, including stored balances, wallets, and cards without having to build and manage an entire banking infrastructure themselves. A regulated player can handle the banking, licensing and compliance requirements, while the platform integrates these services into its own app or website, simplifying and reducing the cost of offering products to users.
The study found that for every core stablecoin use case, about four in ten businesses are already active at meaningful scale, with many other organizations testing or assessing options. Embedded balances, wallets and cards, the most advanced use case, is as widely live as moving money itself (40%), a sign that businesses are already building on stablecoin, not just moving money through it.

Respondents were asked about their predictions for stablecoins over the next three years, and most foresee roles beyond money movement. Across every capability tested beyond payments, including treasury functions, and embedded customer finance, at least 83% of respondents view stablecoin as a priority now or relevant within three years.

More broadly, 82% of organizations expect stablecoins to be part of their financial infrastructure over the next three years. Of these, 45% expect the technology to run quietly behind the scenes and 37% as a core part of how they move money.
Rapid adoption of stablecoins by businesses has fueled the rise of a burgeoning stablecoin ecosystem. According to research by Bearing Technology, a German payment infrastructure consulting firm, this ecosystem now encompasses stablecoin insurers like Circle and Tether; custody and infrastructure providers like Fireblocks, and Utila; payment platforms like BVNK and Bitso Business; cross-border payout networks like TerraPay and Inpay; as well as general payment networks with stablecoin features like Rapyd and Sokin.
This sector’s expansion is also reflected in rising investment. CB Insights estimates that funding to stablecoin companies reached approximately US$12.3 billion in 2025, representing a more than tenfold increase from 2024’s US$1 billion.
Featured image: Edited by Fintech News Singapore, based on image by muhagraph via Magnific
