

For fifty years, core banking systems were designed around one user: a person at a screen.
Screens, workflows, overnight batch, all of it built on the same assumption; that a person clicks the buttons.
That assumption has expired.
AI agents read, decide and act without clicking anything. Instead, agents query data, call APIs and complete tasks on their own. Which means your banking software now has a second user, and it was never designed for one.
This is why so many AI projects in banking stall.
MIT’s Project NANDA found roughly 95% of enterprise generative AI pilots deliver zero measurable return, and around 80% of the work needed to move a pilot into production is data engineering, governance and integration.
Pilots are easy because you can cheat: you use manual data extracts, temporary API keys, and governance exemptions. Production is where the bill comes due.
To go live, those hacks have to become permanent, governed infrastructure and audit-proof APIs, and standard banking cores simply can’t carry that weight.
An AI-native core is one designed for both users at once. In practice, that means three things.
- Governed data foundation: a complete, continuously updated, read-only view of the institution’s data that an AI system can query freely without touching the system serving customers
- Complete API coverage: with real-time event streams, so an agent can act on every function and react the moment something happens: a payment settling, a limit crossing a threshold, a loan maturing
- Safe execution layer: where the institution’s own logic runs inside the core, versioned, auditable and governed, without waiting on a vendor
These help give you faster product innovation, better risk decisions, operational scale and a lower cost of change.
Leaders in the region are already doing this.
Salmon entered the Philippine market on this architecture, scaled to millions of customers and acquired a bank along the way, growing its loan portfolio 648% in twelve months.
FairMoney runs more than 24 million accounts on a single deployment and processes over 8,000 loan applications a day.
Both are running on live data, at volumes most institutions would consider a stress test.
The regulators are moving in the same direction.
OJK published AI governance guidance for Indonesian banking in April 2025, built around accountability, reliability and human oversight, and the BSP has set similar expectations for Philippine institutions.
Read those frameworks closely, and they describe a clear architecture:
- Complete data lineage
- Auditable logic
- Defined points of control
This leaves every institution in the region with the same question: can your core function with AI as a user?
For most, the honest answer today is no.
The encouraging part is that fixing it just means knowing which of the three foundations you’re missing and building from there.
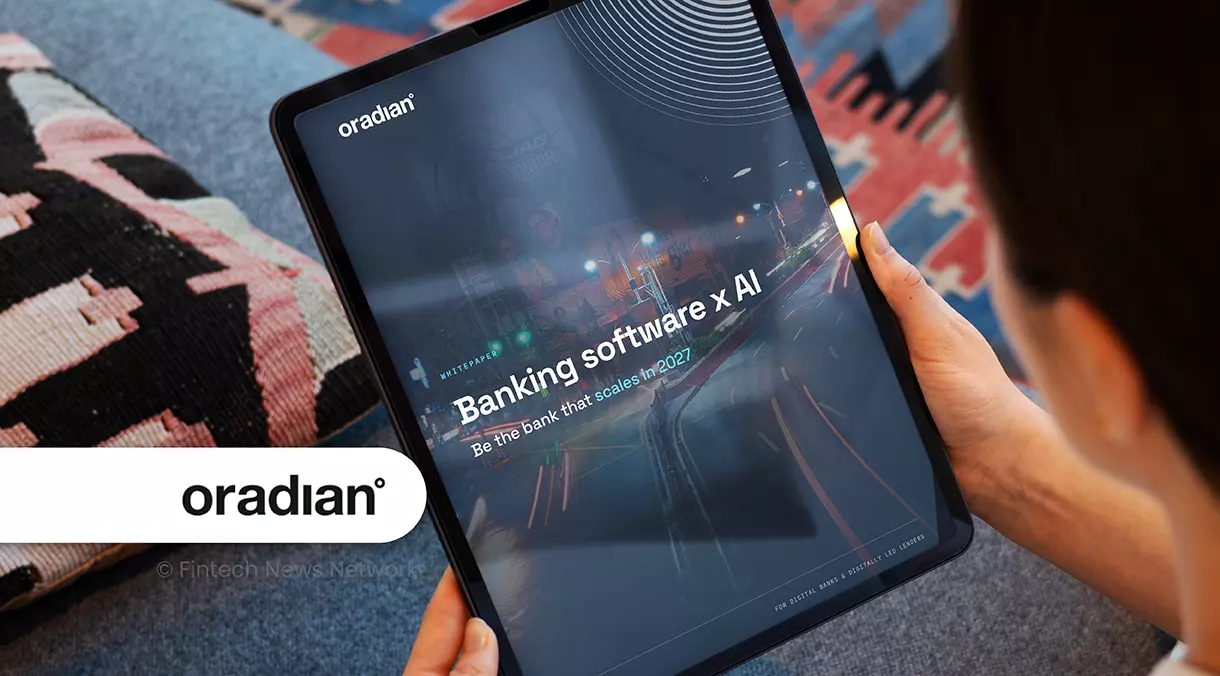
Oradian’s whitepaper, Banking software x AI: be the bank that scales in 2027, supports readers by showing how to scale with AI, including outlining the three planes of an AI-native core, what’s already running in production across the region, and how to accurately judge any core, including ours.
Download the whitepaper: Banking software x AI: be the bank that scales in 2027

Featured image: Edited by Fintech News Singapore based on an image by Magnific.
