

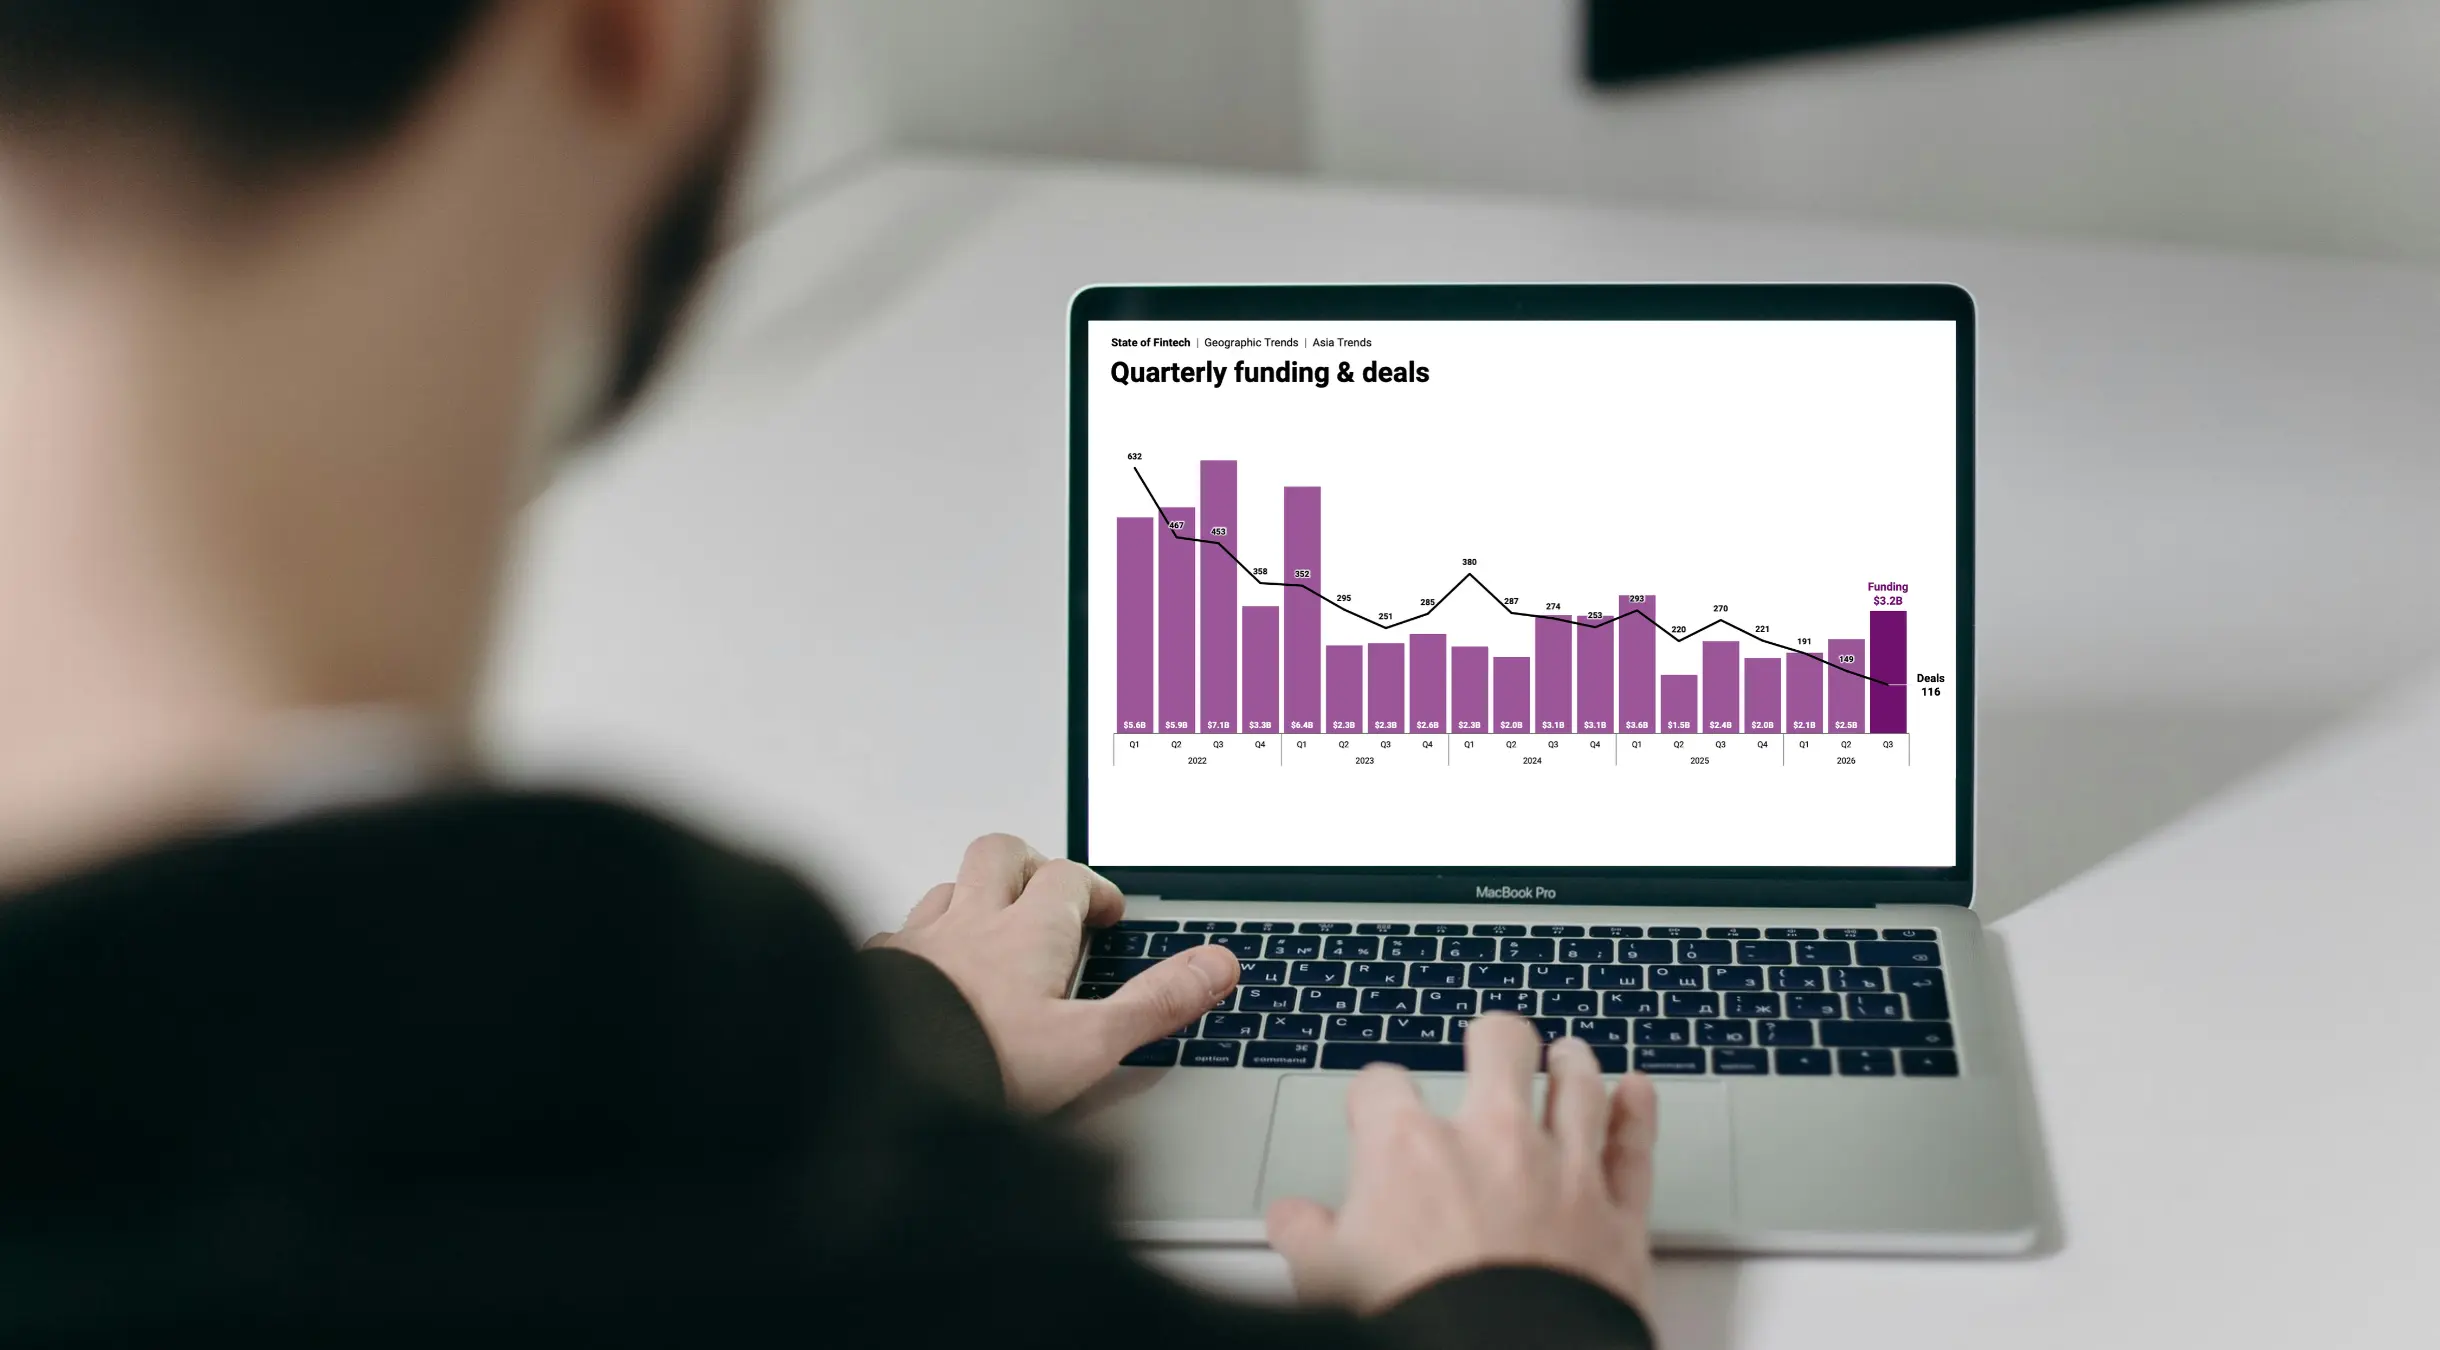
In Q3 2026, fintech companies in Asia raised US$3.2 billion in venture capital (VC) funding, a 28% quarter-over-quarter (QoQ) increase for the region, according to new CB Insights data.
This growth was led by Singapore, which secured US$1.7 billion or 53.1% of the regional total, reaching a record high for the city-state.
Two companies drove much of this amount: Ant International, an independent spinoff of Ant Group offering cross-border digital payments, financial services, and merchants solutions; and Crypto.com, a global cryptocurrency and financial services platform that lets users buy, sell, trade, and spend over 400 digital assets.
Ant International raised a US$1.2 billion Series A in July 2026 to expand globally and accelerate innovation in merchant payment, account management and other financial services for small and medium-sized enterprises (SMEs) and firms across the world.
Ant International, which began independent operation in 2024 and now operates across Asia, Europe, the Middle East and Latin America (LatAm), links over 150 million global merchants with more than 2 billion user accounts.
Crypto.com secured a US$400 million strategic investment in July 2026, reaching a US$20 billion valuation. The funding is expected to accelerate Crypto.com’s expansion into all asset classes, including tokenized securities and derivatives.
Founded in 2016, Crypto.com offers various financial services, including an app, exchange, and non-custodial decentralized finance (DeFi) wallet, non-fungible token (NFT) marketplace, and direct payment service in cryptocurrency for over 100 million users worldwide.

Growth in Singapore fintech funding aligns with the government’s plan to expand support for the sector. In August 2026, the Monetary Authority of Singapore (MAS) pledged S$220 million (US$156 million) over the next three years under the renewed Financial Sector Technology and Innovation Scheme (FSTI 4.0) to strengthen Singapore’s fintech ecosystem and accelerate innovation and technology adoption across the financial sector.
FSTI 4.0 will be implemented through six tracks:
- The Manpower track, designed to connect fintech firms with students and build a pipeline of young talent for Singapore’s fintech ecosystem;
- The Institution Project track, which will aid financial institutions and fintech firms in developing and deploying innovation solutions with a focus on frontier technologies including artificial intelligence (AI), distributed ledger technology (DLT), and quantum technology;
- The AI Pathfinder track, which will support the scaling and adoption of market-ready AI fintech solutions listed on PathFin.ai;
- The Infrastructure and Platform track, which will support industry-wide infrastructure and platforms that improve sector efficiency, productivity and innovation across financial sector;
- The Centre of Excellence track, which will bring together specialized talent and expertise, and support the growth of emerging technologies; and
- The MAS Fintech Awards track, designed to raise Singapore’s global profile as a fintech hub through the Singapore Fintech Festival (SFF) Fintech Excellence Awards and the Global Fintech Hackcelerator (GFH).
These developments build on a strong foundation of Singapore’s fintech sector. The city-state now hosts more than 1,800 fintech firms, employing close to 10,000 professionals across technology, data, AI, compliance, cybersecurity and business roles, according to the central bank.
Global fintech funding in Q3 2026
In Q3 2026, global fintech funding fell 18% QoQ to US$11 billion, the lowest level since Q3 2024. Deal count also decreased, falling 17% to 650. Mega-rounds of US$100 million and over represented 4% of transactions but 61% of funding volume.
In particular, Kalshi’s US$1.5 billion Series G alone accounted for 14% of Q3 funding, showing strong capital concentration. Kalshi is a regulated financial exchange in the US that allows traders to buy and sell contracts on the outcomes of real-world events. It claims annualized revenue above US$4 billion.
Kalshi’s Series G brought the company’s valuation to US$40 billion, according to the Information, nearly double its May 2026 valuation.

Capital markets technology and payments led much of global fintech total. In Q3 2026, capital markets tech secured US$3.5 billion, or 31.8% of all fintech funding.
The vertical secured a total of US$8.6 billion through 398 deals in the first three quarters of 2026. This represents 89% of 2025’s US$9.7 billion total, putting 2026 on track to exceed last year.
Besides Kalshi’s Series G, other notable rounds in Q3 2026 included FNZ’s US$450 million private equity round, Ridgeline’s US$250 million Series E, and CAIS’ US$170 million Series D.
FNZ is an end-to-end wealth management platform and fintech company from the UK, Ridgeline is an AI-native, cloud-based software platform from the US built for the investment management industry, and CAIS is a US fintech platform connecting independent financial advisors with alternative asset managers.

Similarly, paytech startups raised a total of US$15.4 billion during the same period, already reaching 95.7% of 2025’s US$16.1 billion total. Paytech funding totaled US$4.7 billion in Q3 2026, accounting for 42.7% of all fintech investment during that period.
After Ant International and Crypto.com, other key paytech rounds in Q3 2026 included Barq’s US$330 million Series A and Tabby’s US$233 million Series F, both from Saudi Arabia.
Barq is a mobile financial app offering local and international money transfers, virtual and physical Visa cards, subscription management, and global cross-border QR payments, and Tabby is a buy now, pay later (BNPL) and flexible payment services provider.

Fintech accounted for 5.9% of global VC funding in Q3 2026, which totaled US$187 billion. Much of that capital was driven by AI, which captured US$103.3 billion, or 55.2% of the overall amount.
Featured image: Edited by Fintech News Singapore, based on image by GStock07 via Magnific
