

If AI is making fintech teams more productive, should running the business become cheaper?
Investors increasingly expect it to, leaving founders to show how the time their teams save translates into lower operating costs.
Delivering those savings requires choices about which tasks to automate and how employees’ roles change as AI takes on more work.
Customer-facing tasks need particular care, since companies must decide when an agent can act and when a person should step in.
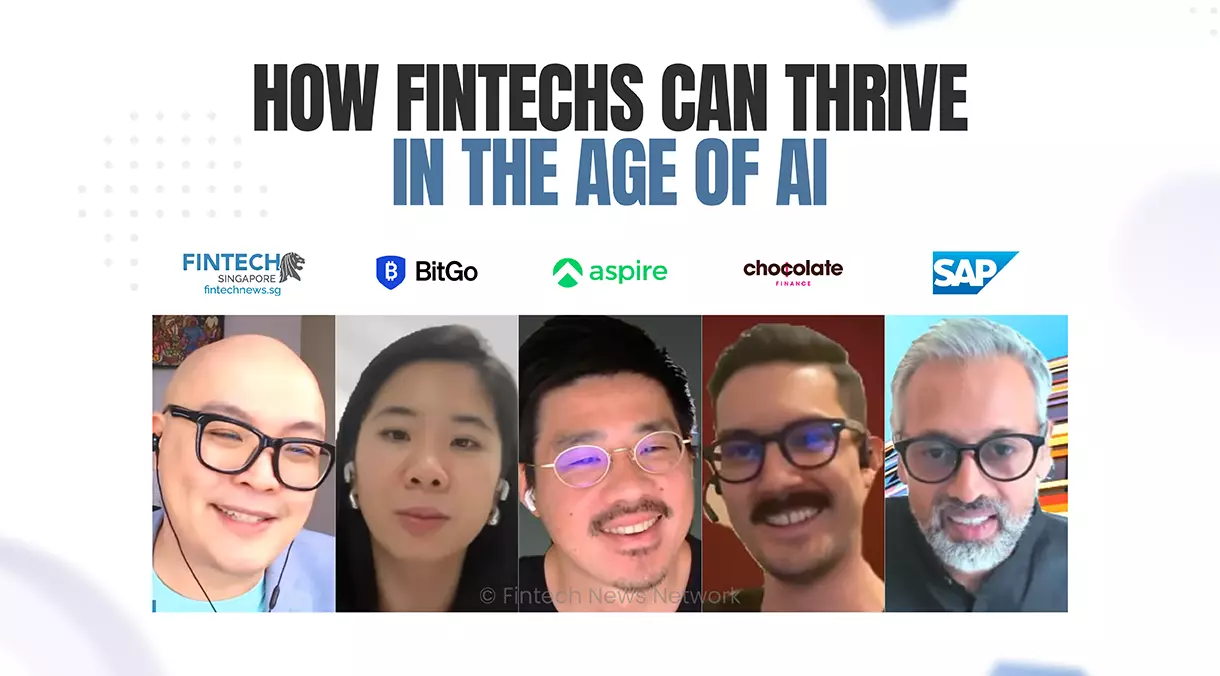
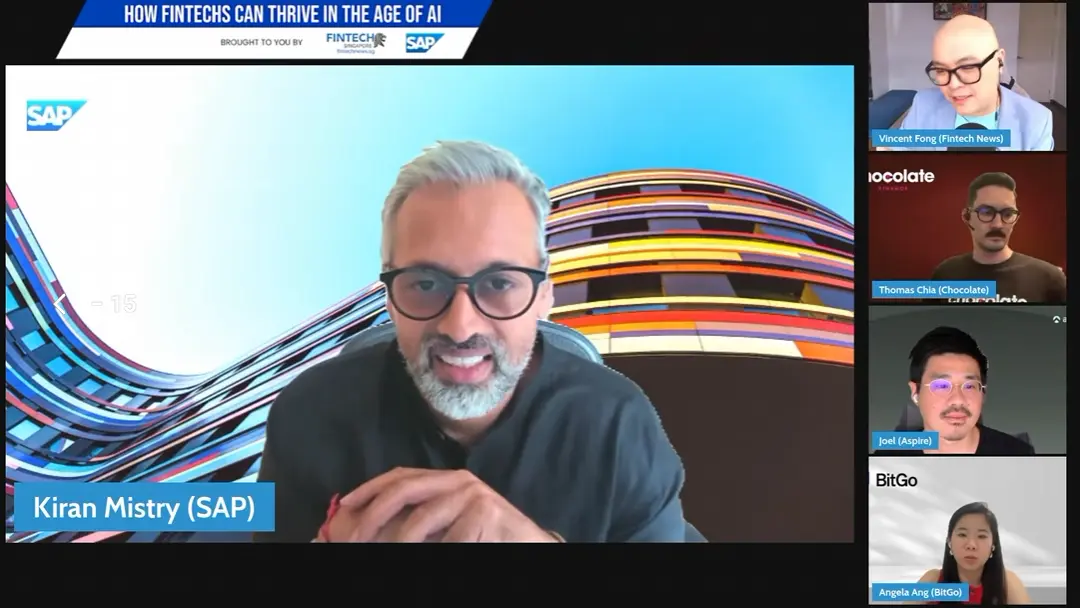
Representatives from Aspire, BitGo, Chocolate Finance and SAP explored how they are making these decisions during How Fintechs Can Thrive in the Age of AI, a webinar sponsored by SAP.
Your Customer May Choose a Different Way In
Joel Leong, Co-founder and Chief Strategy Officer at Aspire, is already seeing some customers send agents to interact with the company on their behalf.
“I think we will be serving agents,” he said.
His prediction raises a question about who fintechs design their services for when a customer delegates the interaction to software.
Aspire is rolling out connections that allow AI tools to interact with its platform, preparing for customers to reach its services through their own agents.
Thomas Chia, Chief Technology Officer at Chocolate Finance, illustrated the possibility with recurring deposits, which its platform already supports.
A future connection could let a customer’s own agent schedule the activity under rules the customer sets.
The example suggests another way for people to control their finances through an interface they choose, with the fintech providing the underlying service.
Can Fintechs Justify Their Costs In an AI Funding Boom?
AI-driven startups attracted US$102 billion, or 64% of global venture funding, in the third quarter of 2026, according to Crunchbase.
Joel described an investment environment where an AI proposition increasingly helps get a conversation started, while board discussions bring closer scrutiny of operating costs and burn.
“There is an expectation from investors that you do pick up some of these productivity gains,” he said.
The implication for founders is that claiming greater productivity invites questions about what changes in the business.
Time saved could reduce running costs or support growth without requiring the back office to expand at the same pace.
Kiran Mistry, Regional Head of Financial Services, APAC, at SAP, heard similar expectations during an investor panel he moderated at last year’s Singapore FinTech Festival.
His takeaway was that a bloated back-office headcount weakened the investment proposition when AI could help run those functions while employees focused on the product.
The investors understood why early-stage fintechs might assemble different systems as they got started, but wanted infrastructure capable of supporting expansion across markets and meeting local compliance requirements.
AI Can Loosen the Engineering Bottleneck
Aspire already tracks adoption, with Joel reporting 70% weekly AI usage across teams and saying that 60% of engineers use AI to write code.
He described significant efficiency gains when employees use the technology effectively, alongside better access to knowledge across the organisation.
Chocolate Finance’s experience shows how those gains can extend beyond completing individual tasks faster.
Thomas explained that internal automation requests traditionally entered an engineering backlog, requiring handovers and decisions about resources.
A sufficiently connected agent can let non-technical employees automate some work through prompts, reducing their dependence on that queue.
Kiran sees opportunities in finance operations, where teams still spend substantial time matching invoices to payments.
SAP embeds agents within its applications’ governance and compliance controls, with customers seeking improvements to cash forecasting and the period-end close.
His accounts clerk example focused on agents taking on manual, time-consuming tasks.
He said automating that work need not eliminate the role, allowing staff to direct more effort towards strategic initiatives.
If AI Can Build It, Why Buy It?
The ability to produce software more easily gives fintechs a reason to revisit systems they would previously have bought.
Thomas, who has traditionally been “bullish on buy”, acknowledged that AI changes the economics of that decision, particularly for engineering teams that know how to build but cannot resource every project.
Earlier in the discussion, he went as far as saying “coding is solved”, while arguing that engineering discipline becomes more important as AI takes on the mechanical work.
The inputs engineers provide and the systems they design carry greater weight.
Teams gaining the ability to produce software through AI face a different calculation if they lack the expertise to support it.
Thomas cautioned against treating development as the whole commitment.
“You are maintaining it. You are operating it. You are decommissioning it when the time is right,” he said.
Who Is the AI Feature Meant to Impress?
Pressure to demonstrate AI adoption can influence what reaches customers.
Asked whether investor expectations help explain why so many AI features feel out of place, Joel admitted the pressure is “part of it”, adding that he favours Thomas’s more deliberate approach.
Chocolate Finance’s product is deliberately simple, Thomas explained, leaving limited scope for AI to improve its core experience in its current form.
Joel described becoming more disciplined at Aspire, where payment speed, cost and reliability guide decisions.
Potential applications include helping customers trace a payment or identifying a cheaper route behind the scenes.
A YouGov survey commissioned by Aspire found that 32% of Singapore SME decision-makers cited AI integration and features as a reason to switch providers, matching the proportion selecting faster transactions.
Nearly 80% wanted at least an equal level of human involvement in customer support.
Joel saw a continuing need for human help when something goes wrong or customers face complex financial decisions.
Thomas offered another perspective. Money is deeply personal, and some people may feel more comfortable discussing their circumstances with AI.
Chocolate Finance is exploring how it could guide prospective customers with less financial knowledge.
Starting With AI Gives New Founders an Advantage
The discipline involved in adding AI to an existing business helps explain why Joel admitted to envying founders starting today.
They can decide how agents fit into workflows and hiring before an operating model takes shape.
Making those changes across an established organisation in several jurisdictions is more difficult, with potential consequences for how quickly it develops and releases products.
Joel weighed that flexibility against the time Aspire has invested in building its network and earning customer and regulatory trust.
Kiran saw opportunities for banks and fintechs to combine established customer relationships with faster development capabilities.
Angela Ang, Managing Director of APAC at BitGo, described a related tension within growing fintechs which is preserving their agility even as larger institutional clients and greater regulatory obligations raise governance expectations.
Institutions still answer for the agents they deploy
The prospect of customers delegating financial tasks to agents makes those governance decisions more consequential.
Angela framed the limit of delegation through a line she had read in an online post.
She outlined four controls institutions need when agents act on their systems.
Identity establishes who stands behind an agent, and permissions set what it can access or execute.
Approval rules separate autonomous actions from those requiring human sign-off, while audit records allow institutions and regulators to reconstruct its decisions.
BitGo already uses AI to support customer queries and access to developer resources.
Angela said extending its use into core financial services requires further consideration of the controls customers and regulators expect.
Singapore’s MAS guidelines on AI risk management, published on 7 October 2026, reinforce institutional accountability.
They take effect on 7 October 2027, with lifecycle controls, including human oversight, phased in by 7 October 2028. Financial institutions retain primary accountability for their use of third-party AI.
Angela expected AI to become a default starting point for transactions and workflows, while arguing that the firms that last will preserve customer and regulatory trust.
“Speed matters, and that’s where AI helps. But so does safety,” she said.
Fintechs preparing to raise capital need finance systems that can support expansion across markets.
GROW with SAP gives growing businesses a subscription option for SAP S/4HANA Cloud Public Edition, allowing them to start with core finance functions and add capabilities as they expand.
SAP says projects with a defined scope can go live in weeks.
Embedded AI agents can help with routine work such as matching invoices to payments, while SAP’s wider localisation portfolio covers more than 130 countries and includes tools for local tax and statutory reporting.
Watch the full discussion in the on-demand playback: How Fintechs Can Thrive in the Age of AI.

Featured image: Edited by Fintech News Singapore based on an image by Fintech News Network via YouTube.
